Is a Watch-Backed Loan Cheaper Than a Merchant Cash Advance?
A cash-flow gap can put a small business owner in a tough spot: payroll is due Friday, but a customer’s invoice will not clear until next month. A merchant cash advance (MCA) may offer a quick route to cash, but its daily or weekly withdrawals can tighten cash flow just when the business needs breathing room. If you own a valuable watch—perhaps a Rolex—a loan secured by that watch may be another option.
So, is a watch-backed loan cheaper than a merchant cash advance? It can be, but there is no automatic winner. The answer depends on the written cost, repayment schedule, loan-to-value amount, fees, and what happens if you cannot repay. A watch-backed loan also puts the watch at risk. Compare actual offers, not the words “fast,” “affordable,” or “pre-approved.”
The short answer: compare dollars, timing, and risk
An MCA is generally structured as a purchase of future business receivables, not a conventional loan. The provider gives you an advance and collects an agreed amount through periodic withdrawals or a share of card sales. A watch-backed loan is typically a secured loan: the lender advances money against a watch it holds as collateral, and you repay under the contract to get the watch back.
Either product may be expensive. An MCA can carry a high effective annual cost, especially when the provider collects quickly. A watch loan may have a lower total dollar cost for a short borrowing period, but interest, origination or storage fees, renewal charges, and a short deadline can change the comparison. The loan may also be smaller than the cash you need because the lender will not usually advance the watch’s full resale value.
What it means for payroll: Choose the repayment schedule your business can meet after rent, wages, taxes, and essential suppliers—not simply the option that deposits money first.
Why a cash-flow gap can make financing feel urgent
Small businesses often face timing mismatches rather than a lack of sales. A contractor may finish a job but wait for an invoice to be approved. A retailer may need inventory before a busy season. A restaurant may have payroll and food invoices due before weekend revenue arrives. In Mesa, Scottsdale, and Tempe, owners also have to plan around seasonal demand, tourism, construction cycles, and customer payment terms.
When the gap is urgent, speed matters. But speed does not make financing cheap. Ask each provider when it will verify the application, complete any valuation or inspection, issue final approval, and release funds. A broker’s initial estimate is not the same as a funded offer. Get the timing in writing and confirm what could delay it.

How merchant cash advance costs work
With an MCA, the provider usually quotes an advance amount and a total payback amount. Some providers also quote a factor rate. For example, a factor rate of 1.30 on a $10,000 advance generally means $13,000 is due before considering any separate fees. That is not an annual interest rate, and it does not show the full cost of borrowing over time. If the provider collects the $13,000 quickly, the effective annualized cost can be much higher than the factor rate may suggest.
Ask the provider for the net amount you will receive after fees, the total amount you must repay, the expected payment amount and frequency, and the estimated payoff date. If payments vary with sales, ask how the provider calculates them and whether the contract permits reconciliation when sales fall. Do not assume that “percentage of revenue” means payments automatically shrink when business slows.
What it means for payroll: A daily debit can leave less cash in the account each morning, even if the business is profitable on paper.
Questions to ask an MCA provider
- What is the exact amount deposited after all fees?
- What is the total amount collected, and how often will the provider collect it?
- Does the contract allow reconciliation if actual sales drop?
- What happens if a payment is returned or the account balance is too low?
- Does the agreement include a personal guarantee, confession of judgment, or restrictions on future financing?
A personal guarantee matters because it may make you personally responsible if the business cannot repay. Read the guarantee itself; do not rely on a salesperson’s summary. The same diligence applies to any watch-loan agreement: find out whether you are personally liable for a remaining balance if the collateral is sold.
How a watch-backed loan works
A collateral-based lender evaluates the watch, determines an amount it is willing to lend, and holds the watch while the loan remains outstanding. The lender may consider the model, reference, condition, originality, box and papers, service history, and the price it could reasonably obtain if it had to sell the watch. The offer will generally be below a retail or optimistic asking price. That difference gives the lender room for resale costs, market changes, and the time needed to sell.
For a secured loan, the watch is the lender’s collateral. If you miss the required payments and do not cure the default as the contract allows, the lender may have the right to take ownership or sell the watch, subject to the agreement and applicable law. Ask how the lender handles default, whether it gives notice, and whether you could owe anything after a sale. A collateral loan does not necessarily require a personal guarantee, but some agreements can include additional obligations. Check the paperwork rather than assuming.
What it means for payroll: You may avoid a daily business-account debit, but you still need enough cash to meet each loan payment and reclaim the watch.
Rolex liquidity: useful, not guaranteed
Rolex has an active secondary market, and some models are easier to resell than others. That liquidity can help a lender evaluate collateral, but it does not mean every Rolex will watch-backed loan command a high price or sell immediately. Model and reference, condition, authenticity, completeness, service history, and current buyer demand all matter. Prices can move, and dealer offers, auction results, and online asking prices are not interchangeable.
Use secondary-market pricing data tracked publicly as a reference point, not as a promise of what a lender will advance. Look for data that identifies the model and reference, dates the observations, and distinguishes completed transactions from asking prices where possible. Compare more than one source and note whether the reported price reflects a private sale, a dealer transaction, or an auction result. A lender may use a more conservative estimate because it must account for resale expenses and the possibility that prices change before it sells the watch.
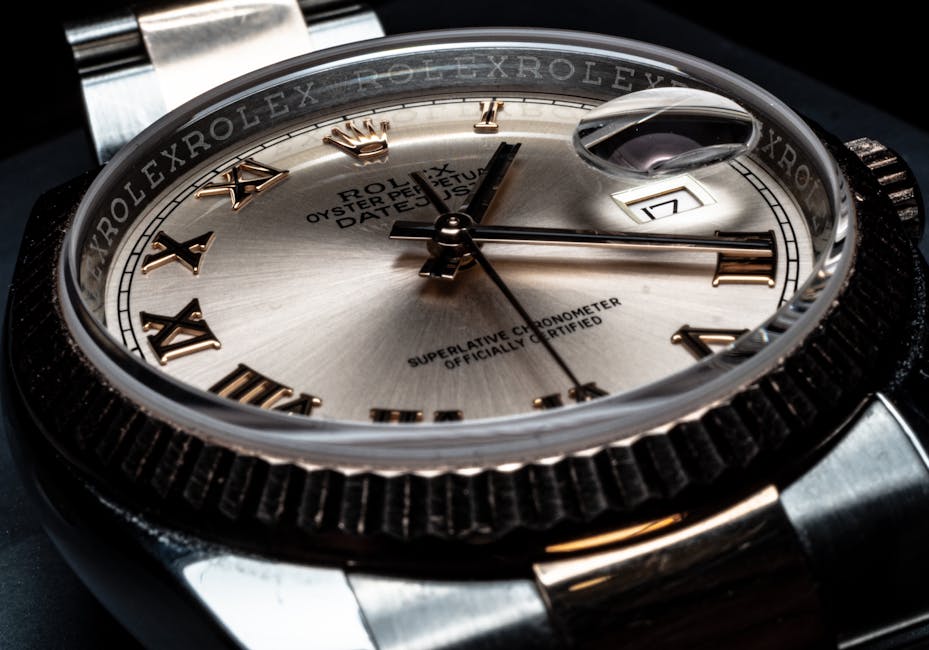
A qualified specialist should authenticate the watch and assess its condition. Authentication can involve examining identifying details, movement, components, and signs of replacement or modification. A photograph or seller’s receipt alone may not be enough. Ask who performs the inspection, what credentials or experience they have, whether the inspection fee is refundable, and what happens if the watch does not pass. Do not hand over a watch without a written receipt that records its identifying details and condition.
Compare the offers side by side
The table below shows what to request from each provider. It does not predict which product will be cheaper; the contract and actual numbers decide that.
Comparison point Merchant cash advance Watch-backed loan Cash received Advance less any withheld fees Loan proceeds less any fees or charges Repayment basis Agreed payback, often collected daily or weekly, sometimes linked to sales Payment schedule stated in the loan contract Cost to compare Total payback minus net proceeds; assess timing and fees Total interest and fees over the expected term; include renewal or storage charges Primary risk Frequent withdrawals may strain operating cash; contract may include personal obligations You may lose the watch after default; some contracts may also create personal liability Key valuation issue Business revenue and repayment capacity Authenticity, condition, resale demand, and conservative collateral value Questions about timing When will underwriting finish and funds arrive? When will authentication, valuation, approval, and funding finish?To compare costs, calculate the net cash you receive and the total dollars you repay. Then map every payment to the date it leaves your account. If the terms differ, ask a qualified accountant or financial adviser to help calculate an annualized comparison; a factor rate and an interest rate are not directly interchangeable. Include fees and any cost of extending or renewing the agreement.
Short-term loan alternatives worth checking
A watch-backed loan and an MCA are not the only short-term loan alternatives. Before pledging a personal asset or accepting frequent withdrawals, ask whether a lower-pressure source could cover the same timing gap:
- Invoice financing: If a reliable customer owes a documented invoice, a provider may advance part of its value. Compare fees, recourse terms, and whether the customer must be notified.
- Business line of credit: A bank or credit union line can provide reusable access to funds, though underwriting may take longer and approval is not guaranteed.
- Supplier terms: A vendor may extend a payment date or split an invoice. Confirm whether the arrangement adds fees or affects future deliveries.
- Customer deposit or milestone billing: For suitable work, revised payment terms can reduce the gap without adding debt.
- SBA-backed financing: Some SBA programs may suit longer-term needs, but they are not usually a same-day fix. Application, documentation, and lender review take time.
These Browse this site options are not automatically cheaper or available on the needed timeline. Ask for a written quote and compare the same basics: net proceeds, total repayment, payment dates, fees, collateral, and personal guarantee.
When each option might fit
A watch-backed loan may fit when
- You need a defined amount for a short, specific gap and can reasonably forecast repayment.
- You own a watch the lender can authenticate and value, and you accept the risk of losing it if you default.
- The written loan cost and schedule are lower or more manageable than the MCA offer you have.
An MCA may fit when
- You have consistent card or other eligible sales and understand exactly how collections work.
- You have compared its total cost with available alternatives and can absorb the withdrawal schedule.
- You understand all contract terms, including default provisions and any personal guarantee.
Neither product fits well if repayment depends on an uncertain sale, a hoped-for new contract, or another loan you have not secured. If you cannot explain where repayment cash will come from, pause before signing.
A practical decision checklist
- Define the gap. Write down the amount needed, the date it is needed, and the expected date cash will arrive.
- Get complete offers. Request the contract, fee schedule, repayment calendar, and any guarantee or collateral agreement.
- Verify the watch value. Check public secondary-market data for the exact reference, then obtain an assessment from a qualified specialist.
- Calculate the cash effect. Put proposed payments beside payroll, taxes, rent, inventory, and other obligations.
- Check the downside. Identify what happens after a missed payment, whether you can cure a default, and whether you could lose the watch or owe a deficiency.
- Compare alternatives. Ask your bank, credit union, customers, and suppliers about options that might solve the same timing problem.
Bottom line
A watch-backed loan can cost less than an MCA in a particular deal, especially when the loan has transparent fees, a manageable term, and a payment schedule that fits the business. But a Rolex’s secondary-market liquidity does not guarantee a high advance, a quick sale, or a low rate. Authentication, condition, market demand, and lender terms all shape the offer.
Compare the actual dollars and due dates, not just the funding speed. The cheapest option on paper may still create a daily repayment squeeze, while a secured loan may put a valuable personal asset at risk. Make sure you know the total cost, the funding timeline, the consequences of default, and whether you are signing a personal guarantee before you use financing to cover payroll.