Is Borrowing Against a Rolex a Bad Idea?
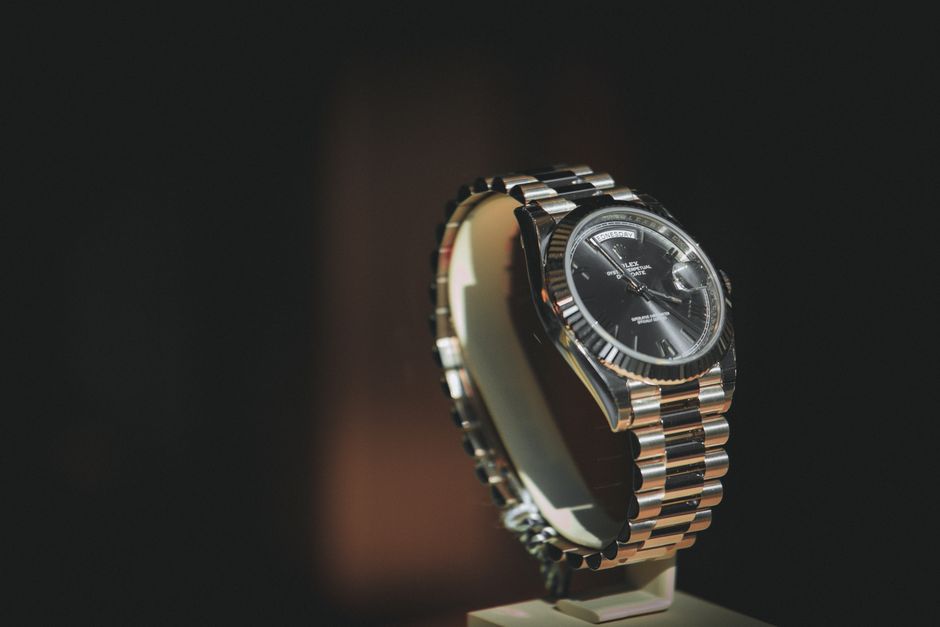
Borrowing against a Rolex can be a practical way to get cash without selling a watch you want to keep. It can also turn a valuable personal asset into collateral for a loan that may be expensive, short-term, and unforgiving if you miss payments. Whether it is a bad idea depends less on the crown on the dial than on the loan terms, your repayment plan, and how much you would regret losing the watch.
In Los Angeles, I’ve seen owners consider a watch loan to cover a business gap, a tax bill, or an unexpected expense. The key question is not simply, “What is my Rolex worth?” It is, “How much will I receive, what will it cost to get it back, and what happens if I can’t?” Here is how to evaluate a short-term liquidity watch loan—and the watch equity loan pros and cons to understand before signing.
What Does It Mean to Borrow Against a Rolex?
A watch-secured loan uses your Rolex as collateral. The lender assesses the watch, makes an offer, and holds it while you repay the loan under the agreed terms. Some arrangements are made through specialist lenders; others may be structured as a pawn loan or another type of secured credit. The legal rules and consumer protections can differ, so check the contract and applicable state requirements rather than assuming every loan works the same way.
The lender’s offer is not necessarily the watch’s resale value. A dealer or lender may account for condition, model demand, service history, how quickly the watch could be resold, and the cost of authentication. The loan amount may also be below the lender’s estimated resale value, leaving a cushion if the market moves or the borrower defaults.
That gap matters. If you have a watch worth more than the amount you borrow, the difference does not automatically make the deal affordable. Interest, fees, storage charges, insurance terms, renewal rules, and missed-payment consequences all affect the real cost.
Why Rolex Resale Values Matter in 2026
Rolex resale values are not fixed, even when a particular reference has a long track record of demand. Prices can shift with interest rates, consumer confidence, supply, collector preferences, and the number of similar watches available. A lender setting an offer today is making a judgment about both the watch in front of them and the market it may face later.
The post-2022 market is a useful reminder. During the pandemic-era surge, prices for many sought-after watches rose sharply. That run-up was followed by a broad cooling period beginning in 2022, as speculative buying eased and secondary-market prices corrected. The adjustment did not affect every model equally: some references fell more than others, and certain watches remained relatively resilient. By 2024 and 2025, market behavior was better described as uneven stabilization than a simple return to peak prices.

In 2026, there are signs of recovery in parts of the Rolex secondary market, but a rebound is not a guarantee that every model is appreciating or that prices will keep rising. For a concrete example, Rolex secondary-market prices rose 1.7% in Q1 2026 vs the previous quarter. That is a period-to-period market indicator—not a promise about the resale value of an individual watch, and not a substitute for a current offer on its exact reference and condition.
Market coverage from sources such as the Los Angeles Times can help readers understand broader luxury and consumer trends. Morgan Stanley’s research on the Swiss watch industry can offer useful context on brands, supply, and market structure. Neither general reporting nor industry research should be treated as a personal valuation. For an owner considering a loan, the watch’s actual reference, condition, documentation, and local buyer demand still matter.
How to Track the Market Before You Borrow
Use multiple data points, and compare like with like. A price estimate for a steel sports model is not a sound guide to a gold dress watch, and a listing price is not the same thing as a completed sale. Before accepting a loan, research the exact reference and, where possible, similar examples with comparable condition, bracelet, box and papers, and service history.
- WatchCharts: A watch-pricing platform that tracks market estimates and price trends. It can help you see direction over time, but an index or estimate may not match the amount a lender will advance.
- EveryWatch: A watch-auction platform that can help you review auction activity and comparable results. Confirm the sale date, currency, condition, and whether any buyer’s premium or other charges are included.
- Dealer and lender offers: Ask more than one reputable business for a written offer. A cash purchase offer and a collateral-loan offer are different products, so compare the terms as well as the headline amount.
Use these sources as a reality check, not as a promise of liquidity. A watch may have a high watch backed loan Beverly Hills asking price online but take time to sell. A lender is likely to focus on what it can recover within its own resale process, not the most optimistic listing you found.
Watch Equity Loan Pros and Cons
Potential advantage Potential drawback You may access cash without selling the watch outright. You may receive less than the watch’s likely retail or private-sale value. The loan may be quicker than applying for some forms of unsecured credit. Fees and interest can make a short loan costly, especially if it is renewed. You may keep the option to reclaim the watch after repayment. Default can put the watch at risk, subject to the contract and applicable law. A secured loan may be available even when other borrowing options are limited. The lender holds an asset that may be difficult or impossible to replace at the same price.The main benefit is access to cash while retaining a path to ownership. The main risks are cost and loss of control over an asset you value. If you need money for a few weeks and have a reliable repayment source, the arrangement may be manageable. If repayment depends on a future bonus, an uncertain business deal, or the hope that the watch rises in value, the risk grows quickly.
Understand the Risk of Not Repaying
The risk of not repaying is more than a late fee. Depending on the contract and the type of loan, you could lose the watch after a specified default process. You may also face renewal costs, additional charges, or other consequences described in the agreement. Do not assume that paying interest alone keeps the watch safe indefinitely; ask exactly what payment is required, by when, and what happens after a missed deadline.
Before handing over a Rolex, get clear written answers to these questions:
- What is the total amount due on the repayment date, including interest and every fee?
- Is there a grace period, and what does a late or missed payment trigger?
- Can the loan be extended or renewed, and what would that cost?
- How will the watch be stored and insured while it is in the lender’s possession?
- What specific process applies if you default, and when could the watch be sold or otherwise disposed of?
- Will the lender provide a detailed intake record, including reference and serial information, condition notes, and photographs?
Take your own clear photographs and keep copies of the paperwork. Record the watch’s condition, accessories, and any known service history. If the watch has sentimental value, factor that into the decision: an emotional attachment can make the cost of losing it much higher than its market price.
Certified Pre-Owned and Resale Credibility
Credibility is especially important when a watch is being valued, sold, or used as collateral. Rolex Certified Pre-Owned (CPO) watches are sold through authorized retailers that participate in the program and meet its requirements. CPO can provide buyers with added confidence through a brand-backed authentication and warranty framework, but it does not mean every pre-owned Rolex in the market is CPO—or that CPO pricing equals what a lender will offer for an unserviced or undocumented watch.
Outside the CPO channel, resale credibility depends on the specific seller and the evidence available. Ask how the watch is authenticated, what is included in the sale, whether the movement and components have been examined, and what recourse is available if a problem is found. A box and papers can support a sale, but they are not a replacement for a proper inspection. Conversely, missing accessories do not automatically make a watch inauthentic; they can, however, affect buyer confidence and the offer.
For a loan appraisal, request a written description of the watch and the basis for the lender’s valuation. A clear, itemized assessment is easier to compare with other https://dibz.me/blog/how-do-i-know-if-my-rolex-has-replacement-parts-1280 offers than a verbal figure delivered across a counter.
When a Rolex-Backed Loan May Make Sense
A short-term liquidity watch loan is most defensible when the need is temporary, the repayment source is specific and reliable, and the total cost is acceptable in advance. It may be worth considering if selling the watch outright would be undesirable and other borrowing options are slower, more expensive, or unavailable. Even then, compare alternatives such as a bank or credit-union loan, a payment arrangement with the creditor, or a direct sale if you no longer intend to keep the watch.
Borrowing is harder to justify when you are using the watch to cover recurring living costs, when you have no firm repayment date, or when repayment depends on another loan. It is also risky to borrow based on a forecast that Rolex prices will continue to rise. Recent recovery can inform a market conversation; it cannot pay your bill on schedule or protect you from a downturn.
A Practical Decision Checklist
- Know the exact reference and gather any service records, purchase documents, and accessories.
- Check current market direction on WatchCharts and review relevant results on EveryWatch, while separating estimates and asking prices from completed sales.
- Get multiple written offers and compare a loan against a direct sale and other borrowing options.
- Calculate the full repayment amount—not just the amount you receive today.
- Make a repayment plan based on money you can reasonably expect, not a hoped-for price increase.
- Read the default and storage terms before leaving the watch with anyone.
The Bottom Line
Borrowing against a Rolex is not automatically a bad idea, but it is not “free cash” either. A watch equity loan trades immediate liquidity for a cost and the possibility of losing a valuable asset. The 2026 resale recovery may be encouraging for some owners, following the post-2022 slump, but watch markets remain model-specific and can change quickly.
Focus on the contract, not just the appraisal. If the total repayment is clear, the lender is credible, and you have a dependable plan to repay on time, a loan may serve as a short-term bridge. If the repayment plan is uncertain—or the Rolex is irreplaceable to you—selling, choosing another form of credit, or not borrowing may be the safer decision.